
The global diamond industry, a fascinating blend of ancient geology and modern commerce, is currently navigating a complex period marked by shifting market dynamics and strategic operational transformations. At the heart of this intricate ecosystem stands De Beers, a name synonymous with diamond mining and distribution for over a century. Despite facing a notable 23 percent dip in its third-quarter (Q3) output for 2023, De Beers has confidently maintained its full-year production forecast, projecting between 30 million and 33 million carats. This unwavering outlook, even in the face of temporary setbacks, signals the company’s long-term vision and strategic resilience. Understanding the nuances behind this Q3 performance—from specific mine transitions to broader macroeconomic pressures—is crucial for anyone looking to grasp the current pulse of the world’s diamond supply chain.
De Beers’ Strategic Pivots: The Venetia Mine Transformation
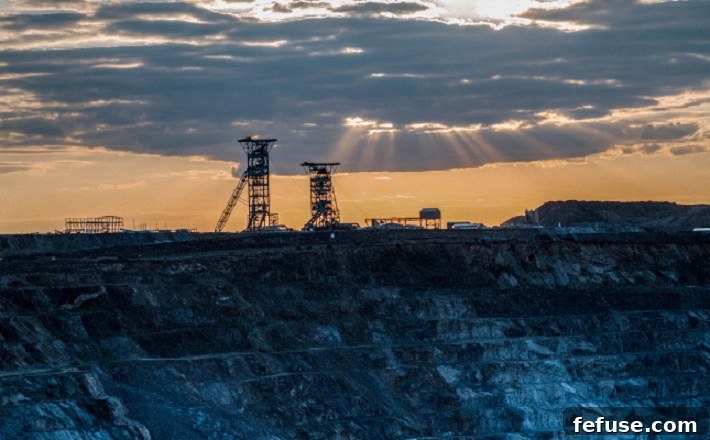
A significant factor contributing to De Beers’ Q3 production decline was the pivotal transition at its Venetia mine in South Africa. Venetia, a cornerstone of South African diamond mining, is undergoing an ambitious and costly transformation from an open-pit operation to an underground mine. This switch, representing a monumental investment of approximately $2 billion, is not merely a change in mining technique but a strategic move designed to extend the mine’s life by several decades and secure a stable supply of high-quality diamonds well into the future. Such a project underscores the long-term commitment required in the diamond industry, where multi-billion-dollar investments yield returns over many years.
Understanding the Transition’s Impact
The immediate impact of this large-scale engineering feat on production has been substantial. In Q3 2023, output from Venetia plummeted by a staggering 78 percent, dropping from 1.65 million carats in Q3 2022 to just 365,000 carats. This sharp reduction is an expected, albeit temporary, consequence of such a complex operational shift. The transition involves an immense amount of preparatory work, including shaft sinking, tunnel development, and the installation of new infrastructure, all of which naturally constrain active diamond extraction.
While the initial phase of excavation has been completed, allowing Venetia to resume production, output levels are not yet back to historical norms. The mine is currently focusing on processing lower-grade surface stockpiles. This approach allows for continuous operation and revenue generation during the ramp-up phase of the underground mine, but it inherently means a lower yield of carats compared to direct extraction from richer ore bodies. The long-term benefits of this transition, however, far outweigh the short-term production fluctuations. Once fully operational, the underground Venetia mine is expected to provide a consistent supply of diamonds, contributing significantly to De Beers’ overall portfolio and reinforcing South Africa’s role in the global diamond supply.
Global Production Snapshot: A Deeper Look into Q3 2023 Performance
Beyond the Venetia transformation, De Beers’ overall Q3 production witnessed a significant contraction, falling from 9.1 million carats in Q3 2022 to 7.4 million carats in Q3 2023. This 19% reduction reflects a combination of factors across its various operations. De Beers, through its joint ventures, operates across several key diamond-producing nations, each presenting its own set of operational conditions and market influences.
Botswana: A Cornerstone with Planned Interruptions
Botswana remains the bedrock of De Beers’ production, largely through its partnership with the government in Debswana. However, even this powerhouse saw a 12 percent decline in output during Q3. This decrease was primarily attributed to planned maintenance activities at the Orapa mine, one of the world’s largest diamond mines by area. Routine maintenance is an essential part of mining operations, ensuring the longevity and efficiency of machinery and infrastructure. While necessary, such planned shutdowns can temporarily affect production volumes. The strategic importance of Botswana to De Beers cannot be overstated; its mines, including Jwaneng (often considered the richest diamond mine in the world by value) and Orapa, consistently produce high-quality diamonds that are vital to the company’s global supply.
Canada and Namibia: Regional Variances
De Beers’ Canadian operations also experienced a downturn, with production dropping by 9 percent. The Canadian diamond mining landscape, while known for producing some exceptional quality stones, can be challenging due to its remote locations and harsh climatic conditions. Factors such as geological variances, operational adjustments, or even specific market demands for certain types of Canadian diamonds could contribute to such a decline. In contrast, production in Namibia remained unchanged. Namibia is particularly significant for its marine diamond mining operations, which involve recovering diamonds from the seabed off the coast. This specialized form of mining often yields high-value stones, and its consistent output provides a stable component to De Beers’ diverse production profile.
Navigating a Cautious Market: Sightholders and Midstream Inventory
The challenges faced by De Beers in Q3 2023 extend beyond operational adjustments; they are deeply intertwined with the prevailing market conditions. The company’s “sightholders”—a select group of diamond buyers who purchase rough diamonds directly from De Beers—have adopted an increasingly cautious approach. This hesitancy is clearly reflected in the sales figures, with a mere $200 million in sales recorded earlier in the month, a stark indicator of the prevailing market sentiment.
The Impact of Macroeconomic Headwinds
De Beers explicitly attributed this caution to “the uncertain macro-economic environment and high levels of diamond inventory in the midstream.” The global economy has been grappling with a confluence of factors: persistent inflation, rising interest rates, geopolitical tensions, and a general tightening of consumer discretionary spending. These macro-economic headwinds inevitably ripple through the luxury goods market, with diamonds being particularly sensitive to consumer confidence and disposable income. When consumers feel less secure about their financial future, or when the cost of living increases, luxury purchases often take a backseat.
The Midstream Inventory Challenge
The concept of “high levels of diamond inventory in the midstream” is critical to understanding the current market dynamics. The midstream of the diamond pipeline comprises the cutters and polishers who transform rough diamonds into finished gems. When these players accumulate significant inventories of polished diamonds that are slow to sell to retailers, their demand for new rough diamonds naturally diminishes. This backlog can occur for several reasons, including:
- **Slow Retail Sales:** If consumers are buying fewer polished diamonds, retailers reduce their orders from polishers.
- **Overproduction:** Periods of strong demand might have led to an increase in polishing activity, resulting in excess supply when demand subsequently softens.
- **Financing Costs:** Holding large inventories ties up capital, and in an environment of rising interest rates, the cost of financing these inventories becomes more expensive, further pressuring midstream players to reduce stock.
This inventory overhang creates a bottleneck, dampening the appetite for rough diamonds, even from a major supplier like De Beers. The rough diamond sales figures underscore this trend: 7.4 million carats from three Sights in Q3 2023, compared to 9.1 million carats (8.5 million carats on a consolidated basis) from three Sights in Q3 2022, and 7.6 million carats from two Sights in Q2 2023. The consistent decline indicates a persistent reluctance from buyers to commit to large purchases, forcing De Beers to adapt its selling strategies.
De Beers’ Strategic Response: Fostering Equilibrium
In response to these challenging market conditions, De Beers is taking proactive steps to support its sightholders and re-establish market equilibrium. The company announced its commitment to “continue to support its Sightholders to help re-establish equilibrium between wholesale supply and demand by providing full flexibility for rough diamond allocations in Sights 9 and 10 of 2023.” This strategy is designed to inject much-needed flexibility into the diamond pipeline, allowing sightholders to manage their inventory and financial commitments more effectively.
What “Full Flexibility” Means for Sightholders
Providing “full flexibility” during rough diamond allocations typically entails several measures:
- **Reduced Purchase Obligations:** Sightholders might be allowed to defer purchases or buy less than their usual allocated volumes without penalty.
- **Tailored Assortments:** De Beers may offer more customized rough diamond assortments, allowing buyers to select stones that are in higher demand or more suited to their current inventory needs.
- **Payment Terms:** Potentially more flexible payment terms or extended credit periods could be offered to ease financial pressure on the midstream.
- **Market Intelligence Sharing:** Collaborating more closely with sightholders by sharing market insights and demand forecasts to help them make more informed purchasing decisions.
The ultimate goal of these measures is to alleviate the pressure on the midstream, allowing them to clear their existing polished diamond inventory before committing to significant new rough diamond purchases. By carefully managing the flow of rough diamonds into the market, De Beers aims to prevent further oversupply and support a healthier pricing environment throughout the diamond value chain. This collaborative approach recognizes that the health of De Beers is intrinsically linked to the financial stability and operational success of its sightholders and the wider diamond industry.
Future Outlook and Industry Resilience
Despite the Q3 headwinds, De Beers’ confidence in maintaining its full-year production forecast for 2023 speaks volumes about its long-term strategy and operational strengths. This optimism likely stems from a combination of factors: the expected ramp-up of production from the newly transitioned Venetia mine, the inherent strength and efficiency of its Botswanan operations (with planned maintenance now completed), and an anticipation of gradual market stabilization. While the macroeconomic environment remains unpredictable, the underlying demand for natural diamonds, especially in key luxury markets, is expected to rebound as economic conditions improve.
The diamond industry is known for its cyclical nature, characterized by periods of robust growth followed by phases of consolidation and adjustment. De Beers, with its extensive experience and global reach, is well-equipped to navigate these cycles. Its ongoing investments in sustainable mining practices, ethical sourcing, and innovative marketing strategies (including campaigns promoting the unique value of natural diamonds) position it strongly for future growth. The company’s commitment to supporting the entire diamond pipeline, from mining to retail, underscores its dedication to the long-term health and prosperity of this precious industry. As the world continues to value rarity, beauty, and emotional connection, natural diamonds, with De Beers at the forefront, are set to retain their coveted place in the luxury market, albeit through a landscape that demands continuous adaptation and strategic foresight.