
ALROSA’s Diamond Sales: Navigating Market Dynamics in Early 2019
ALROSA, the undisputed global leader in diamond mining, has released its sales figures for April and the cumulative first four months of 2019. These reports offer crucial insights into the performance of the world’s largest diamond producer amidst a period characterized by notable shifts and challenges within the global diamond market. As a bellwether for the industry, ALROSA’s results highlight both the underlying strength of demand for rough diamonds and the prevailing headwinds faced by the midstream segment of the value chain.
Detailed Sales Performance: April 2019 Overview
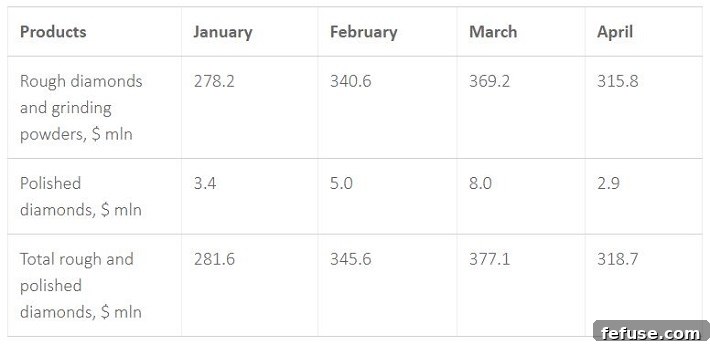
In April 2019, ALROSA reported total sales of rough and polished diamonds amounting to an impressive $318.7 million. A closer examination of these figures reveals a clear distinction in demand across different segments. Rough diamond sales formed the overwhelming majority of this total, reaching $315.8 million. This figure underscores the consistent appetite among diamond manufacturers and cutters for raw materials, even in a fluctuating market.
In contrast, sales of polished diamonds stood at a more modest $2.9 million for the month. While ALROSA primarily operates as a rough diamond supplier, its polished diamond sales offer a glimpse into the immediate consumer market sentiment. The disparity between rough and polished sales often indicates inventory adjustments or cautious purchasing behavior further down the diamond pipeline, particularly at the retail and wholesale levels.
Cumulative Sales Performance: January-April 2019
Looking at the broader picture for the initial four months of 2019, ALROSA’s total sales of rough and polished diamonds reached $1,322.9 million. This cumulative figure provides a comprehensive overview of the company’s performance during the first third of the year. Breaking down this total, rough diamond sales accounted for a substantial $1,303.8 million, reinforcing ALROSA’s dominant position in supplying the raw material that fuels the industry.
Polished diamond sales during this four-month period totaled $19.2 million. While a small fraction of the overall sales, these figures are a testament to ALROSA’s diversified approach, albeit with a primary focus on rough diamond extraction and supply. The consistent volume of rough diamond sales, despite the market’s complexities, demonstrates the fundamental, long-term demand for diamonds that underpins the industry.
Understanding the Market Dynamics: Challenges and Outlook
Evgeny Agureev, Member of the Management Board and Director of the United Sales Organization at ALROSA, provided a candid assessment of the prevailing market conditions. He noted, “In the first months of 2019, the global diamond market saw a somewhat weaker demand from cutters and polishers due to both diamond stock normalization as mid-streamers in India continue to experience difficulties with access to affordable financing, and inherent cyclicality of the market.” This statement highlights two critical factors influencing the diamond industry’s performance during this period.
Financing Challenges for India’s Mid-Streamers
The global diamond value chain heavily relies on the mid-stream segment, primarily located in India, where the vast majority of rough diamonds are cut and polished into the exquisite gems seen in jewelry stores worldwide. Agureev’s comments underscore a significant hurdle faced by these crucial players: access to affordable financing. Over the past few years, stricter lending norms from banks, often a reaction to past defaults and increased scrutiny of the diamond industry’s financial practices, have made it challenging for cutters and polishers to secure the necessary capital for their operations. This tightening of credit can lead to reduced purchasing power for rough diamonds, directly impacting miners like ALROSA, as mid-streamers manage their inventory more cautiously.
The lack of readily available and affordable credit can create a bottleneck in the supply chain. When mid-streamers struggle to finance new rough diamond purchases, it slows down the entire process from mining to retail. This situation often leads to a buildup of inventory at the mining stage or a reduction in demand for new rough stones, directly contributing to the “weaker demand” observed by ALROSA.
Diamond Stock Normalization and Market Cyclicality
Another key factor mentioned is “diamond stock normalization.” This refers to the adjustment of inventory levels throughout the supply chain. In periods of strong demand, companies might build up higher stock levels to meet anticipated future sales. Conversely, when demand softens or becomes uncertain, these companies tend to reduce their inventories to align with current market realities, thus “normalizing” their stock. This process can temporarily depress demand for new rough diamonds as existing inventories are worked through.
Furthermore, the “inherent cyclicality of the market” is a fundamental characteristic of the luxury goods sector, to which diamonds belong. The diamond market is sensitive to broader macroeconomic trends, consumer confidence, and discretionary spending. Periods of global economic slowdown or uncertainty often translate into reduced demand for luxury items, leading to cyclical downturns. These cycles are a natural part of the industry’s rhythm, and experienced players like ALROSA continuously adapt their strategies to navigate these ebb and flow patterns.
ALROSA’s Resilience and Strategic Outlook
Despite these challenges, ALROSA maintains a “moderately positive outlook for the foreseeable future,” with an expectation that “the market situation [will] improve in the second half of the year.” This measured optimism reflects ALROSA’s deep understanding of the market and its robust position as the world’s largest diamond producer by volume. The company’s ability to manage its production, sales channels, and inventory allows it to weather short-term fluctuations.
Several factors could contribute to an anticipated improvement in the latter half of 2019. Typically, the second half of the year benefits from key retail seasons, including the Diwali festival in India, the Christmas holiday season in Western markets, and Chinese New Year preparations. These periods traditionally see a surge in consumer demand for diamond jewelry, which can reinvigorate the entire supply chain. Additionally, any potential easing of financing conditions for Indian mid-streamers or a stabilization of global economic indicators could also catalyze market recovery.
The Broader Diamond Industry Context
ALROSA’s performance and outlook are intertwined with the health of the broader global diamond industry. The journey of a diamond from mine to finger is complex, involving numerous stages and geographical hubs. After extraction by companies like ALROSA, rough diamonds are typically sorted and sold. From there, they enter the mid-stream, predominantly in cutting and polishing centers in India, Belgium, Israel, and China. Once polished, diamonds move to wholesalers and then finally to retailers who sell them to end-consumers in key markets such as the United States, China, and Europe.
Each segment of this value chain is susceptible to its own set of pressures. The challenges faced by Indian mid-streamers, for instance, have a ripple effect, impacting the demand for rough diamonds from miners and potentially influencing the availability and pricing of polished diamonds for retailers. ALROSA’s strategic positioning, including its long-term supply agreements and diversified customer base, helps mitigate some of these risks, allowing it to maintain a relatively stable operational footing even during periods of market softness.
Visualizing ALROSA’s Performance
To further illustrate the sales performance, a visual representation of ALROSA Group’s rough and polished diamond sales for January-April 2019 is included. This graphic provides a clear snapshot of the proportions and totals discussed, offering an easy-to-understand overview of the company’s financial activity during this crucial period.
Conclusion: A Leading Miner’s Perspective on a Dynamic Market
ALROSA’s sales report for April and the first four months of 2019 paints a picture of a resilient leader navigating a complex and dynamic market. While the initial months of the year presented headwinds stemming from financing constraints in the mid-stream segment and natural market cyclicality, the company’s strong rough diamond sales figures underscore the underlying demand for its core product. The “moderately positive outlook” for the second half of the year reflects a strategic optimism rooted in anticipated seasonal demand and potential market stabilization. As the global diamond industry continues to evolve, ALROSA remains a pivotal player, consistently adapting its strategies to ensure sustained growth and stability within this fascinating and enduring luxury market.