
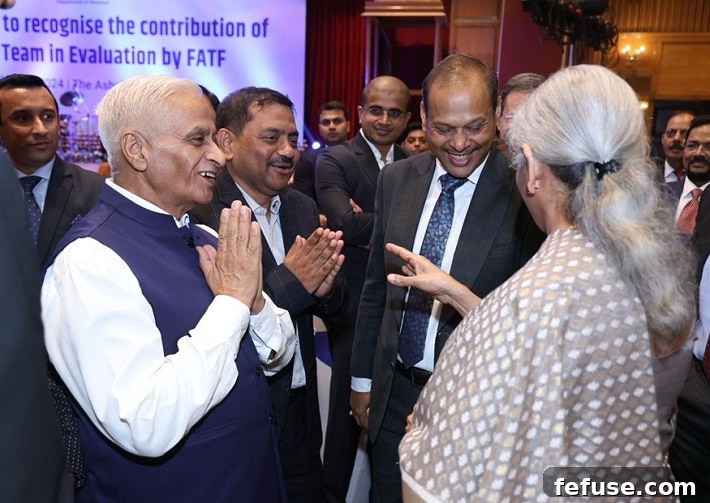
India’s unwavering commitment to global financial integrity received significant recognition on June 29th, as the Revenue Department hosted a celebratory get-together. This esteemed event, held at The Ashok Hotel in New Delhi, marked the successful conclusion of India’s rigorous Financial Action Task Force (FATF) Mutual Evaluation (ME) process. The occasion not only commemorated the nation’s robust preparedness, heightened awareness, and diligent implementation of FATF standards but also served as a platform to laud crucial contributions from various stakeholders, notably the Gem & Jewellery Export Promotion Council (GJEPC). Presiding over this pivotal gathering was the Hon’ble Minister of Finance and Corporate Affairs, Smt Nirmala Sitharaman, whose leadership has been instrumental throughout this complex journey. The final report, a testament to India’s dedicated efforts, was formally tabled at the FATF plenary session on June 26th, 2024, cementing India’s strong position on the global financial stage.
The path towards a successful FATF Mutual Evaluation is inherently challenging, demanding an intense and meticulously coordinated effort across multiple governmental and private sectors. India’s comprehensive preparation and execution were exemplary. The core Indian team comprised dedicated professionals from a broad spectrum of critical government bodies, including the Department of Revenue, the Ministry of Home Affairs, the Ministry of Corporate Affairs, and the Ministry of External Affairs. Beyond these, numerous other ministries, a multitude of financial sector regulators, various law enforcement agencies, and key figures such as judges and prosecutors played indispensable roles. This intricate network extended to a vast array of public and private sector players, all of whom faced the stringent FATF assessment with remarkable coordination, transparency, and sincerity. This collective achievement is particularly noteworthy and stands as a beacon of national commitment, especially when considering the global financial landscape. Many G20 countries, including economic powerhouses like the USA, China, Germany, Canada, and Japan, are currently navigating enhanced follow-up procedures within the FATF framework. Furthermore, countries such as South Africa and Turkey find themselves on the FATF’s grey list, underscoring the gravity and significance of India’s successful clearance. This context elevates India’s accomplishment, showcasing its proactive stance in adhering to the highest international anti-money laundering (AML) and counter-terrorist financing (CTF) standards.
The gem and jewellery sector, due to its global reach, high-value transactions, and intricate supply chains, is often identified as a particularly sensitive area concerning financial transparency and regulatory compliance. Recognizing this inherent sensitivity, the Indian government placed immense importance on ensuring the complete satisfaction of the FATF Review Team regarding the sector’s adherence to AML/CTF guidelines. Consequently, the GJEPC, the apex body representing India’s vibrant gem and jewellery industry, was strategically involved in the FATF Mutual Evaluation process from its nascent stages. This proactive engagement culminated in a critical final presentation and intensive discussions with the Review Team, which took place in Delhi in November 2023. Under the astute leadership of its Executive Director, Mr. Sabyasachi Ray, the GJEPC team meticulously prepared and delivered a substantive presentation. This detailed exposition offered an exhaustive explanation of the various compliances rigorously adhered to by the Indian gem and jewellery trade. The presentation highlighted the industry’s robust internal controls, stringent Know Your Customer (KYC) norms, comprehensive transaction monitoring systems, and proactive suspicious transaction reporting mechanisms. It underscored the sector’s commitment to ethical sourcing, transparent business practices, and continuous training programs designed to enhance awareness and implementation of regulatory requirements, thereby safeguarding its reputation and ensuring its contribution to a legitimate global economy.
The meticulous efforts and unwavering contributions of the GJEPC did not go unnoticed. The FATF Review Team expressed full satisfaction with the industry’s compliance framework and the comprehensive information provided. As a direct acknowledgment of their pivotal role and exemplary commitment, the GJEPC was extended a special invitation to the high-profile get-together organized by the Revenue Department. This prestigious event, a celebration of national achievement in financial compliance, saw the Hon’ble Minister of Finance and Corporate Affairs, Smt Nirmala Sitharaman, gracing the occasion as the Chief Guest. Her presence underscored the government’s appreciation for the collaborative spirit and diligent work demonstrated by all involved. The gathering was attended by a distinguished roster of senior officials and dignitaries, reflecting the wide-ranging inter-agency cooperation that contributed to India’s success. Notable attendees included the Revenue Secretary, the DEA Secretary, and high-ranking officials from critical regulatory and enforcement bodies such as the Central Board of Indirect Taxes and Customs (CBIC), the Central Board of Direct Taxes (CBDT), the Directorate of Revenue Intelligence (DRI), the Enforcement Directorate, and the Reserve Bank of India (RBI). Their collective presence symbolized the united front presented by India in upholding global financial standards and fostering an environment of transparency and accountability.
Expressing his profound gratitude and immense pride, Mr. Vipul Shah, Chairman of the GJEPC, shared his insights on this significant milestone. “Our team’s unwavering dedication and thorough preparation have been absolutely crucial in achieving this successful review,” Mr. Shah remarked. “We are deeply honored to receive this recognition for our collective efforts. This acknowledgment further strengthens our resolve to not only uphold but continuously elevate the highest standards of compliance within our industry.” His statement resonated with the broader sentiment of commitment to integrity and responsible trade practices that permeated the event. The successful outcome of India’s FATF Mutual Evaluation reinforces the nation’s standing as a trustworthy and compliant global financial partner. For the gem and jewellery sector, this success translates into enhanced credibility, greater market access, and a distinct competitive advantage in international trade. It reassures global stakeholders that India’s precious goods are traded through channels that adhere strictly to international anti-money laundering and counter-terrorist financing norms. This positive assessment is expected to bolster investor confidence, facilitate smoother international business dealings, and attract further foreign direct investment into the sector, which is a significant contributor to India’s economy and export revenues. More broadly, it signals India’s enduring commitment to fostering an environment of financial transparency and accountability, crucial for sustainable economic growth and global stability.
Looking ahead, India’s successful navigation of the FATF Mutual Evaluation process serves not as an endpoint, but as a robust foundation for continuous improvement. The government, in close collaboration with industry bodies like the GJEPC, remains steadfast in its resolve to adapt and strengthen its regulatory frameworks in line with evolving global best practices. This ongoing commitment ensures that India not only meets but proactively anticipates and addresses new challenges in the fight against financial crime. For the gem and jewellery industry, this means an enduring focus on training, technological adoption for better compliance monitoring, and fostering a culture of integrity at every level of the value chain. The experience gained during this intensive evaluation will be invaluable in refining existing policies and developing innovative solutions to maintain the sector’s impeccable record. This collaborative spirit, uniting government agencies, regulators, and the private sector, exemplifies India’s holistic approach to national financial security and its role as a responsible global citizen. The success celebrated on June 29th is a powerful testament to India’s capability to implement complex international standards effectively and serves as an inspiring blueprint for other nations striving for excellence in financial governance. It underscores that through dedication, robust preparation, and seamless collaboration, a nation can achieve remarkable milestones in strengthening its financial ecosystem and safeguarding its economic future against illicit activities.