
De Beers Rough Diamond Sales Witness Decline Amidst Shifting Market Dynamics
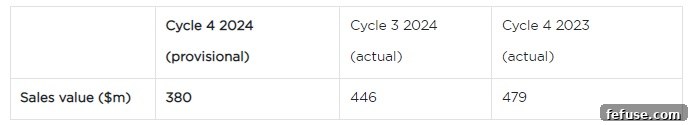
De Beers, a global leader in diamond exploration, mining, and marketing, recently announced its rough diamond sales figures for the fourth sales cycle of 2024, revealing a noticeable decline. This announcement has prompted industry analysts and stakeholders to closely examine the underlying factors contributing to this trend and what it signifies for the broader diamond market. The provisional sales value for this cycle stands at $380 million, a 15% reduction from the $446 million recorded in Cycle 3, 2024. Furthermore, this figure represents a more significant 21% drop when compared to the $479 million achieved in Cycle 4, 2023. Such fluctuations are not uncommon in the dynamic world of luxury goods, but they do warrant a deeper dive into current market conditions and future projections for the diamond industry.
Analyzing De Beers’ Latest Sales Figures: A Closer Look at the Downturn
The reported sales figures from De Beers offer a crucial snapshot of the current health of the rough diamond sector. A provisional value of $380 million, while substantial, indicates a cooling in demand compared to immediate past performance and year-on-year comparisons. The 15% sequential drop from Cycle 3 to Cycle 4 within the same year suggests a recent deceleration in purchasing activity from sightholders – the term De Beers uses for its selected customers who buy rough diamonds directly from them. This immediate dip could be attributed to a confluence of short-term factors impacting the market’s liquidity and sentiment.
More significantly, the 21% decrease from Cycle 4 of the previous year (2023) highlights a broader trend of softening demand over a longer period. This annual comparison provides a more robust indicator of market shifts, suggesting that the current challenges are not merely cyclical but might reflect deeper economic or structural changes. For De Beers, these figures directly impact revenue and profit margins, while for the wider industry, they serve as an early warning sign for potential adjustments in production, pricing strategies, and inventory management across the diamond pipeline, from mining to retail.
Key Factors Influencing the Current Market Slowdown
De Beers Group CEO Al Cook provided valuable insights into the primary drivers behind the observed decline. His statement points to a combination of expected seasonal patterns and specific regional events, alongside broader macroeconomic pressures. Understanding these factors is crucial for appreciating the nuances of the global diamond trade.
Seasonal Fluctuations and the Q2 Effect
As Al Cook noted, “De Beers’ rough diamond sales in the fourth cycle of the year trended lower, in line with the seasonally slower second quarter.” The diamond industry, much like many other consumer-driven sectors, experiences distinct seasonal cycles. The second quarter (April-June) is often considered a quieter period for rough diamond sales following the heightened activity leading up to major gifting holidays in the first quarter, such as Valentine’s Day and Chinese New Year. Retailers typically stock up significantly in the latter part of the previous year and early Q1 to meet holiday demand. By Q2, inventories might still be settling, and new orders for rough diamonds tend to slow down as cutters and polishers work through existing stock and anticipate future retail trends rather than immediate high demand.
Furthermore, many major trade shows and retail events that stimulate demand for polished diamonds often occur later in the year, preparing for the crucial holiday shopping season. This natural ebb and flow in the supply chain means that a slight dip in Q2 sales is often an anticipated part of the annual business cycle, though the extent of the current decline suggests additional pressures are at play.
India’s Role: Elections and Trading Activity
Another significant factor highlighted by the CEO is “a quieter period of trading in India during the elections.” India holds an unparalleled position in the global diamond industry, serving as the world’s largest cutting and polishing center. The vast majority of the world’s rough diamonds pass through Indian facilities before being transformed into polished gems ready for retail. Beyond its manufacturing prowess, India is also a substantial consumer market for diamonds, particularly during wedding seasons and festivals.
National elections in India are massive undertakings that can often lead to a temporary slowdown in economic activity. Businesses, including those in the diamond sector, may adopt a wait-and-see approach due to uncertainty surrounding potential policy changes, shifts in consumer sentiment, or simply because of the logistical disruptions and focus diverted by the electoral process. For a period, large transactions might be deferred, new investments put on hold, and overall trading volumes reduced. Given India’s critical role in the diamond pipeline, any slowdown in this region inevitably reverberates across the entire industry, affecting demand for rough diamonds from producers like De Beers.
Global Macroeconomic Headwinds and Consumer Confidence
Al Cook also touched upon macroeconomic issues in the US, stating that “Demand trends in the US are expected to be driven by short term macroeconomic issues.” The United States remains the single largest market for diamond jewelry, particularly for engagement rings. Consequently, the health of the US economy and consumer spending patterns have a profound impact on global diamond demand. In recent times, the US economy has faced challenges such as persistent inflation, which erodes purchasing power, and higher interest rates, which can make borrowing more expensive and generally temper consumer enthusiasm for luxury discretionary purchases.
When consumers feel the pinch of rising living costs, they often prioritize essential spending over luxury items like diamond jewelry. Economic uncertainty can also lead to increased savings rates and a reduction in non-essential expenditures. This cautious consumer behavior directly translates into lower sales for retailers, which in turn reduces their demand for polished diamonds from manufacturers, and ultimately, lowers demand for rough diamonds from miners. These short-term macroeconomic pressures create a challenging environment for the luxury sector, making it difficult for diamond sales to maintain robust growth.
The Road Ahead: Industry Events and Future Demand Drivers
Despite the immediate challenges, the diamond industry is known for its resilience and adaptability. Leaders like De Beers are already looking ahead to key events and underlying trends that could support a recovery.
The Significance of JCK Las Vegas
“The focus of the global diamond industry now turns towards the JCK jewellery show in Las Vegas at the end of May,” Cook highlighted. The JCK Las Vegas show is one of the most important annual events for the global jewelry industry. It serves as a crucial platform for retailers, manufacturers, designers, and suppliers to showcase new collections, network, gauge market sentiment, and place orders. The timing of JCK is strategic, often setting the tone for the latter half of the year, particularly ahead of the critical holiday shopping season.
For many, JCK is a barometer for the industry’s health and future direction. Manufacturers and retailers will be closely observing attendance, buying activity, and new product introductions to assess consumer trends and overall market confidence. A strong showing at JCK, characterized by robust orders and positive sentiment, could inject much-needed optimism into the diamond supply chain and potentially signal a rebound in demand for rough diamonds in subsequent cycles.
The Post-Pandemic Engagement Boom: A Catalyst for Recovery?
Perhaps one of the most promising long-term demand drivers mentioned is the anticipated recovery in engagements. Al Cook expressed optimism, stating, “Demand trends in the US are expected to be driven… supported in coming years by a recovery in engagements as the after-effects of pandemic lockdowns fade.” The COVID-19 pandemic significantly disrupted social gatherings and life events, including engagements and weddings. Many couples postponed their plans, leading to a temporary dip in demand for engagement rings.
However, demographers and industry analysts have long predicted a “wedding boom” or a surge in engagements once the immediate after-effects of the pandemic subside and life returns to a more predictable rhythm. As social restrictions ease, travel resumes, and consumer confidence slowly rebuilds, couples who delayed their plans are now moving forward. This demographic wave, often referred to as “revenge engagements” or “catch-up engagements,” could provide a significant boost to the diamond jewelry market over the next few years. Engagement rings are a cornerstone of diamond demand, and a sustained recovery in this segment would offer a robust foundation for market growth, offsetting some of the short-term macroeconomic headwinds.
Beyond the Headlines: Broader Trends Shaping the Diamond Industry
While De Beers’ sales figures offer a current pulse, the diamond industry is also undergoing significant structural changes driven by evolving consumer preferences, technological advancements, and a heightened focus on ethics.
Evolving Consumer Preferences: Ethical Sourcing and Sustainability
Today’s consumers, particularly younger generations, are increasingly conscious about the provenance and ethical footprint of their purchases. This applies significantly to luxury items like diamonds. Demand for ethically sourced, conflict-free, and sustainably mined diamonds has grown considerably. Consumers want assurances that their diamonds have not contributed to human rights abuses or environmental degradation. De Beers, through initiatives like its “Building Forever” sustainability framework, focuses on responsible practices, community development, and environmental stewardship, aiming to meet these evolving consumer expectations and maintain its reputation as a trusted supplier.
The Rise of Lab-Grown Diamonds
The emergence and increasing acceptance of lab-grown diamonds (LGDs) present both a challenge and an opportunity for the traditional diamond industry. LGDs offer an identical chemical and physical composition to natural diamonds but are typically available at a lower price point. While De Beers has historically championed natural diamonds, it also entered the LGD market with its Lightbox brand, recognizing the segment’s appeal for fashion jewelry and lower-priced items. The co-existence of natural and lab-grown diamonds requires clear differentiation and marketing strategies to educate consumers and maintain the distinct value proposition of each.
Supply Chain Dynamics and Geopolitical Influence
The global diamond supply chain is complex and can be impacted by various geopolitical events. Sanctions on certain diamond-producing nations, political instability in mining regions, or disruptions in shipping lanes can all affect the availability and pricing of rough diamonds. Companies like De Beers must continuously navigate these complexities, ensuring a stable and ethical supply to meet global demand, while adhering to international regulations and responsible sourcing practices.
Navigating Volatility: De Beers’ Strategy and Market Resilience
De Beers, with its long history and dominant position in the diamond market, has weathered numerous cycles of boom and bust. The company’s strategy typically involves careful management of rough diamond supply to maintain market stability, coupled with strong marketing efforts to stimulate consumer demand for natural diamonds. Its ability to adapt to changing market conditions, invest in innovation, and uphold ethical standards will be crucial in navigating the current volatility.
De Beers’ long-term vision emphasizes the enduring emotional value of natural diamonds, leveraging their rarity and billion-year geological journey. By focusing on consumer education and maintaining brand prestige, De Beers aims to reinforce the unique appeal of natural diamonds, even as the market evolves with new product categories and consumer preferences. The company’s resilience lies in its deep understanding of the market, its robust operational capabilities, and its commitment to responsible practices across its entire value chain.
Conclusion
De Beers’ latest rough diamond sales figures for Cycle 4, 2024, undoubtedly reflect a challenging period for the diamond industry. The decline is attributed to a combination of seasonal slowdowns, the temporary impact of elections in India, and broader macroeconomic pressures affecting consumer spending in key markets like the US. However, these short-term headwinds are viewed within the context of a longer-term outlook that offers reasons for optimism.
The upcoming JCK Las Vegas show is eagerly anticipated as a potential catalyst for renewed market confidence and activity. More significantly, the anticipated recovery in engagements as the lingering effects of the pandemic fade is expected to provide a robust foundation for sustained demand in the coming years. Coupled with evolving consumer preferences for ethical sourcing and the industry’s adaptation to new categories like lab-grown diamonds, the global diamond market is undergoing a period of transformation. While volatility is a constant, the inherent allure of diamonds, backed by responsible industry practices and strategic market development, ensures that the sector remains poised for future growth, albeit with careful navigation through its current complexities.